What Buyers Should Know About Insurance, Financing & Cost
You found a home you love. The price looks right. Then you see it: Lava Zone 2
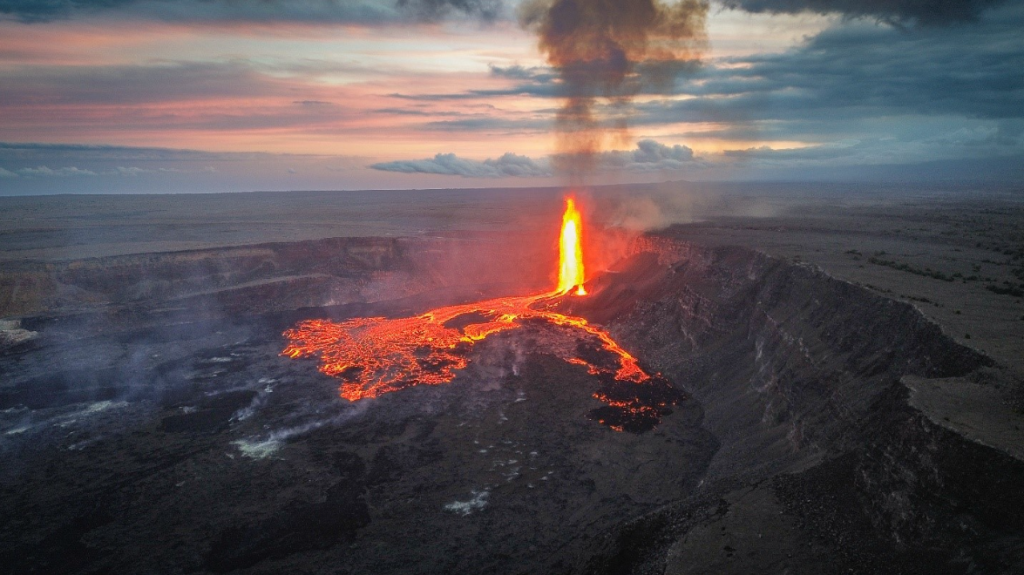
So, what does that actually mean? The USGS divides Hawaiʻi Island into nine lava-flow hazard zones, with Lava Zones 1–2 carrying the highest relative hazard and Zones 5–9 the lowest. A higher lava zone doesn’t automatically mean you should walk away, but it does mean you should understand how it may affect insurance, financing, and the cost of owning the home.
Insurance can be one of the biggest considerations. In Lava Zones 1 and 2, traditional homeowners’ insurance can be harder to obtain and more expensive. In the absence of traditional homeowner’s insurance, HPIA (Hawaii Property Insurance Association) may offer basic coverage as a last-resort option for primary residence purchases. Before making an offer, find out what coverage is available, what it costs, and whether it meets your lender’s requirements. It’s also important to look beyond the listing price. A $350,000 home with $5,500/year insurance could cost more over time than a $400,000 home with $1,500/year insurance.
So, should you automatically avoid a higher lava zone? Not necessarily. Before making an offer, verify the property’s lava zone, get an insurance quote, confirm your financing, and consider other costs like taxes, HOA fees, utilities, and maintenance. At Salt Water Real Estate, we believe buying a home is about understanding what you’re actually buying so you can make a confident decision.
Have questions about a property? We’re here to help you ask the right questions.
Whether you buy, sell, or stay—salt water heals everything.